Buying near Whiteman AFB or Fort Leonard Wood is not the same as buying in a big metro. The housing stock is smaller, PCS dates are real, and a sloppy pre-approval falls apart when the seller wants a clean VA file. Dan Pfenenger is a Navy veteran and a VA mortgage broker with UMortgage, a branch of Nexa Lending. He is a member of Vetted VA, and he works those files for families in Knob Noster, Warrensburg, Sedalia, St. Robert, Waynesville, Lebanon, and Rolla.
What a VA loan actually does
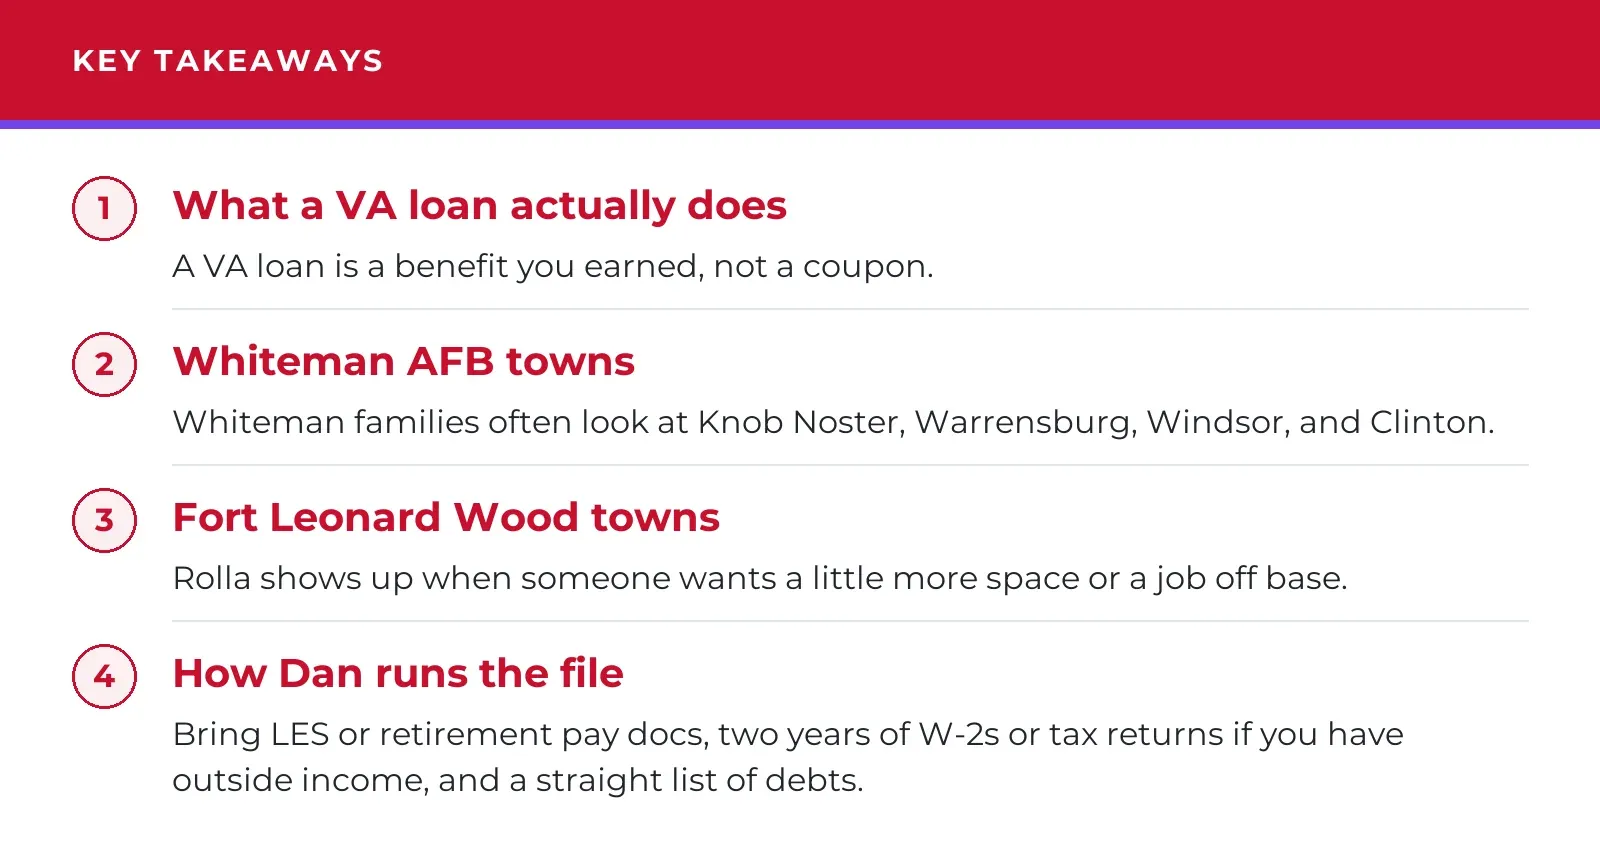
A VA loan is a benefit you earned, not a coupon. When you qualify, many buyers can purchase with no down payment and no monthly PMI. Funding fees, residual income tests, and occupancy rules still apply. Entitlement and any prior VA use have to be checked before anyone should talk about a maximum price.
Money out of pocket on a VA purchase is often the prepaid items, escrows, and any funding fee the seller does not cover. The monthly payment still has to clear residual income. Dan will put both numbers on the table before you tour houses so more of your money stays in your pocket where you expected it, not in a closing surprise.
Dan does not treat that as fine print. If a prior VA loan is still open, or if the property is a fixer that will not meet minimum property requirements, he would rather say so on day one than after you have a contract.
Whiteman AFB towns
Whiteman families often look at Knob Noster, Warrensburg, Windsor, and Clinton. PCS windows are tight, and BAH math has to line up with the payment you can actually carry. Rural properties and manufactured homes can be VA-eligible in some cases and a dead end in others. Build extra time if the house sits on acreage or needs repairs. More on this area at VA loans near Whiteman AFB.
Fort Leonard Wood towns
Fort Leonard Wood families often look at St. Robert, Waynesville, and Lebanon. Rolla shows up when someone wants a little more space or a job off base. The commute and school choices are different from the Whiteman side of the state, so the file still has to match the house and the report date. Appraisers in these counties are not interchangeable with a suburban panel from another state. More on this area at VA loans near Fort Leonard Wood.
How Dan runs the file
Bring LES or retirement pay docs, two years of W-2s or tax returns if you have outside income, and a straight list of debts. Residual income is the VA's way of asking whether the family can still eat after the mortgage hits. A high score does not skip that test.
If you are a veteran truck driver, 1099 income and per diem need a paper trail. Dan works those files, but they take longer than a W-2 teacher on base. Plan for that before you write an offer dated the week you leave for a trip.
What he will not do
He will not tell you the VA always waives something. The work is here: Whiteman, Fort Leonard Wood, the lake, and the towns in between, plus Springfield, Joplin, St. Joseph, and Jefferson City when that is where you actually live.
Next step
Call (573) 761-7400 to start a VA conversation with numbers attached.
This is not a commitment to lend. All loans are subject to credit approval and underwriting. Property must meet program guidelines. Programs and terms can change. Dan Pfenenger, NMLS #2767718. UMortgage powered by Nexa Lending, Company NMLS #1660690. Equal Housing Lender.